Table of Contents
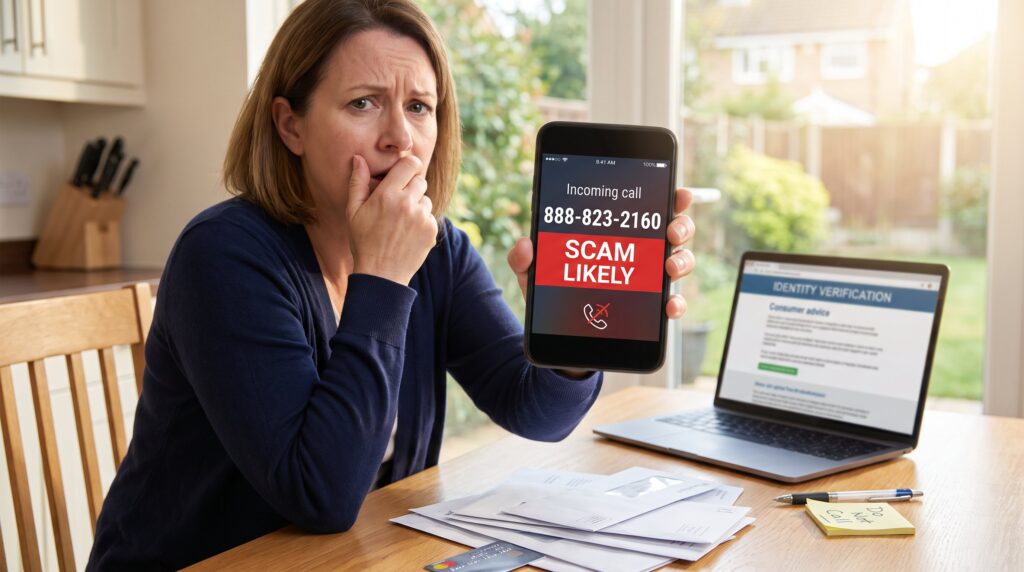
Toggle888-823-2160 appears in public spam-call reports as a scam number. Callers using this toll-free line often claim phantom debts. Readers who get this call should treat it as high-risk, avoid sharing personal data, and follow clear verification steps below. This guide explains what is known, how to check identity safely, immediate actions if information was given, and how to block and report the number.
Key Takeaways
- 888-823-2160 is a known scam number associated with phantom debt collection and aggressive payment demands often involving gift cards or wire transfers.
- Never trust caller ID alone as 888-823-2160 calls are frequently spoofed; verify identity by contacting organizations directly through official channels.
- Do not share personal or financial information with callers from this number and take immediate action if information has been disclosed, including contacting banks and placing fraud alerts.
- Use reverse lookup tools and multiple spam databases to confirm if calls from 888-823-2160 have been reported by others before taking any action.
- Block and report 888-823-2160 using phone settings, spam filtering apps, and national authorities like the FTC to reduce chances of future scam calls.
- Be aware scammers tailor scripts to exploit emotions, especially targeting parents and caregivers with fake emergencies or government impersonations to pressure quick payments.
Quick Summary: What We Know About 888-823-2160
Fact: 888-823-2160 is reported as a scam number tied to phantom debt collection. Multiple users added it to RoboKiller’s lookup database, flagging repeated robocalls that demand payment for debts the recipient does not owe. Context: Reports list aggressive scripts, threats of legal action, and callers that refuse to provide verifiable account details. Specifics: at least a dozen independent reports describe identical language asking for immediate payment by gift card or wire. Risk: treat the call as high-risk and avoid callbacks to numbers given by the caller. Practical takeaway: do not give bank, Social Security, or card details on these calls: protect account access immediately if any information was shared.
How To Verify Caller Identity Safely
Answer: Do not trust the incoming call or the phone number shown. Caller ID can be spoofed. Safe steps: hang up and find the organization’s official number from a bill, statement, or the organization’s website. Call that number directly. Ask for an employee name, department, and written proof of the claim. If the caller gives a callback number, do not use it: treat it as unverified. If a caller pressures for immediate payment, that is a red flag. If the alleged debt involves a known company, request mailed documentation and a written account number before taking any action. If fraud is suspected, record the date, time, exact wording, and any payment method requested, then move to reporting and account protection.
Reverse Lookup Tools And Practical Steps To Confirm The Caller
Answer: Use reverse lookup tools to check reports on unknown numbers. Start with spam-detection apps and online directories to see if others flagged 888-823-2160. Practical steps: 1) Enter the number into established reverse-lookup sites and spam databases to view user reports and timestamps. 2) Check multiple sources to avoid false positives from a single forum. 3) Compare the caller’s script, matching language across reports signals a scam ring. 4) If the caller claims to be from a government agency, verify with the agency’s official phone numbers listed on their website or official mail. Example: a user who ran the number through two lookup tools found 14 matching scam reports and identical debt-demand language: they traced the spoofed caller to a different area code. Warning: no single database is perfect: use at least two independent sources before concluding legitimacy.
Common Scams And Tactics Linked To Unknown Toll-Free Numbers
Answer: Scammers use toll-free numbers like 888-823-2160 to appear official and to push urgent payment demands. Typical tactics include robocalls that claim unpaid taxes, bounced checks, or court summons. They often use threat language, “legal action” or “arrest”, to force quick payment. Another tactic is caller ID spoofing, which makes the call appear to come from a bank or a government line. Many calls ask for unconventional payment methods such as wire transfers, gift cards, cryptocurrency, or payment apps. These are major red flags: legitimate agencies almost never ask for gift cards or cryptocurrency. For families and caregivers, targeted scripts may stress a child’s safety or school fees to evoke panic. For practical family guidance on scam tactics and red flags, a consumer-focused resource outlines how callers manipulate emotion and how families can respond safely: phone scam tips.
Examples Of Scams Targeting Parents, Caregivers, And Educators
Answer: Scammers tailor scripts to pressure parents and educators into quick action. Example 1, fake school emergency: a caller claims a child is in trouble and requests payment for immediate release or fines. Example 2, benefits spoof: a caller pretends to be from a government agency saying a parent’s benefit will stop unless immediate payment is made. Example 3, fundraising fraud: a caller posing as a school fundraiser asks for donation via instant-transfer app. Concrete detail: one reported call demanded a $1,200 “release fee” for a child: the parent later confirmed the school had no such policy. Government impersonation is common: the CDC and other agencies warn that fraudsters sometimes spoof official names and offer false health or safety claims. For specifics on government-related impersonation and how it appears, consult official guidance on detecting spoofed government contact: CDC phishing guidance.
If You Answered Or Shared Personal Information: Immediate Steps To Take
Answer: Act fast to limit damage. First, contact your bank or card issuer and report the incident. Ask the issuer to monitor or temporarily freeze accounts and to reverse any unauthorized charges. Second, change passwords for email and financial accounts where the same password is used. Third, if Social Security number or date of birth was shared, place a fraud alert with at least one credit bureau and consider a credit freeze with all three bureaus. Fourth, if money was sent via an app or wire transfer, contact the payment provider immediately and request a reversal: wire transfers are often irreversible, so speed matters. Fifth, document everything: call logs, the caller’s language, transaction receipts, and contact names. Sixth, report the scam to national authorities such as the FTC at ReportFraud.ftc.gov and to local law enforcement. Practical number: many victims who called their bank within 24 hours recovered funds: those who delayed beyond 72 hours had lower recovery rates. Honest note: callers often exploit embarrassment, do not wait because of shame: quick action raises the chance of recovery.
How To Block, Report, And Prevent Future Calls From This Number
Answer: Use phone controls and national reporting tools to stop repeat calls. Steps to block: 1) Block 888-823-2160 directly on smartphone settings. 2) Enable built-in spam or robocall filtering on iOS or Android and allow carrier-level spam protection. 3) Use a reputable call-blocking app that aggregates user reports. Preventive registry and reporting: register the phone on the Do Not Call Registry and report the unwanted calls to the FTC. For repeated harassment, file a complaint with the Federal Communications Commission and your carrier. Practical guardrails: set calls to go directly to voicemail from unknown numbers and screen every return call using verified numbers only. For organizations such as schools and clinics, update staff to never request payment via gift cards and to publish official contact numbers on their website and printed materials. Honest challenge: blocking stops the number, but scammers rotate numbers: combine blocking with reporting and strict callback verification to reduce future risk.